Gen X Has a Timing Problem: Protecting Wealth at Every Stage
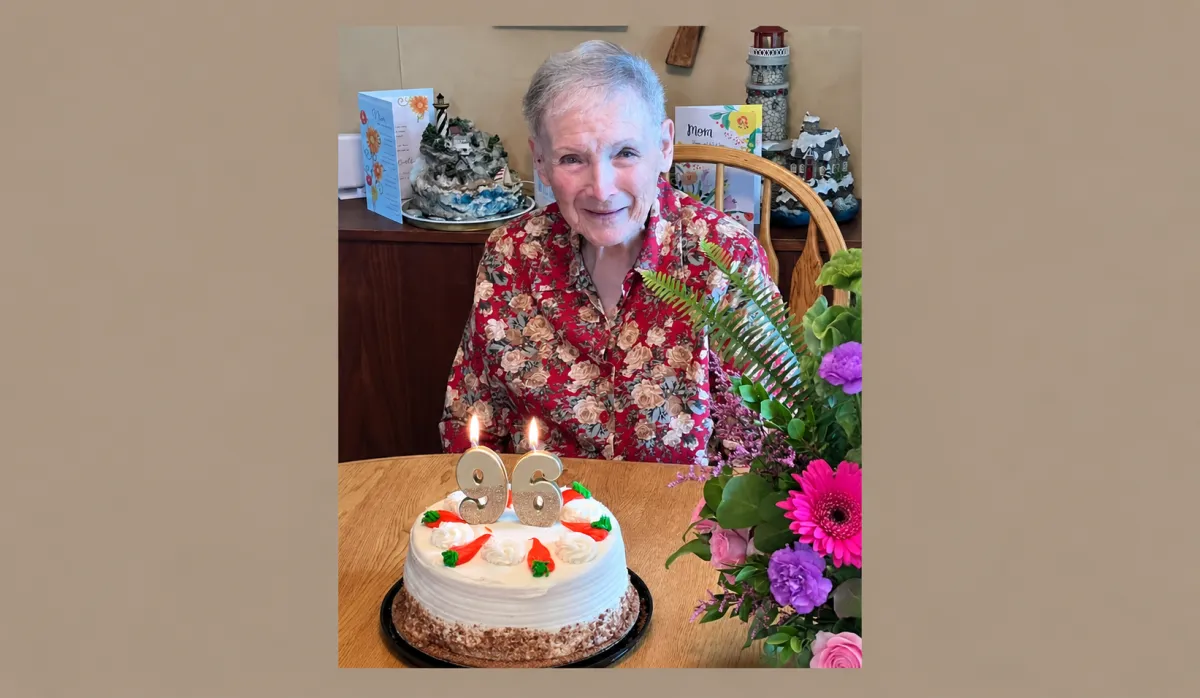
My grandmother turned 96 last week. She still lives alone, remains remarkably independent, and just renewed her driver's license.
When she was 50, there was no reasonable way for her to know that nearly half a century of life might still be ahead of her. That's what makes longevity such a hard financial variable to plan around. We can make assumptions about retirement, income, health, and life expectancy, but none of us actually knows how much time we're planning for.
For Gen X, that uncertainty is getting harder to ignore. Many of us have accumulated meaningful assets, but we're also still carrying real obligations: a mortgage, kids who aren't fully independent yet, aging parents who need support, businesses that still depend heavily on us, retirement goals that assume another decade or two of earning and investing.
That creates a problem with two very different sides. What happens if we live much longer than expected? And what happens if we don't get all the earning years we assumed we would? Those aren't the same risk, and they don't call for the same solution.
The Timeline Works Both Ways
Living longer creates an obvious challenge. If retirement lasts thirty years instead of fifteen, income and assets have to stretch to cover a much longer life. That's where conversations about reliable income later in life start to matter.
My grandmother makes that risk easy to picture. The opposite risk gets a lot less attention, and it's just as real.
A 50-year-old planning to work until 65 may still be counting on fifteen more years of income, retirement contributions, mortgage payments, business growth, and investing. A couple might have a retirement strategy that only works if both people keep earning. A business owner might be counting on another decade of growth before selling or handing off the company. A meaningful part of the wealth we expect to have later doesn't exist yet. It still has to be created, which raises an uncomfortable question: what happens if the income stops before the obligations do?
Different Problems Require Different Protection
This is where conversations about life insurance tend to get too simple. We talk about "having life insurance" like it's one problem with one solution, but it isn't.
For a family that still leans heavily on someone's income, the priority may be replacing that income during the years when kids are still dependent, the mortgage is still large, or retirement assets are still being built. That's often the kind of temporary exposure term life insurance is built to cover.
Housing adds its own version of the problem. A family can have substantial equity in a home and still need two incomes to make the payment. If one income disappears, the issue isn't the value of the house, it's whether the surviving family can afford to keep it. That's the real question behind mortgage protection.
Later in life, the concern often looks different. Someone may no longer need decades of income replacement, but might still want cash available for funeral costs, final expenses, or outstanding debt. That's where smaller permanent or final-expense coverage tends to fit.
Some needs are temporary. Others are meant to exist no matter when death occurs, because someone wants money available for a spouse, kids, heirs, or another long-term obligation whether that happens next year or thirty years from now. That's where permanent coverage enters the conversation.
Business owners carry an extra layer, because the financial impact can reach well past the household. If a company depends heavily on one owner for revenue, relationships, leadership, or debt obligations, that owner's death can hit partners, employees, customers, and the value of the business itself.
These are genuinely different situations, but they share the same underlying question: what becomes financially vulnerable if the timeline changes?
The Problem Changes as Life Changes
Our financial lives rarely look the same at 50 as they did at 35. Kids grow up. Mortgages get refinanced. Income changes. Businesses get built or sold. Marriages begin and end. Parents become dependents. Assets grow. Debts disappear. New responsibilities take their place.
A policy bought ten or fifteen years ago might still be exactly right. It might also be solving a problem that no longer exists while leaving a newer risk completely unaddressed. That's why asking whether someone "has life insurance" doesn't tell you much. The better question is whether the protection still matches the life.
The Real Issue Is Uncertainty
My grandmother's 96th birthday keeps bringing me back to the same conclusion: Gen X has to think about two different timelines at once.
One asks whether our money can support us if we live much longer than expected. The other asks whether the people, obligations, and plans that depend on us would stay financially stable if we're not here as long as expected. One problem might call for dependable income later in life. The other might involve term coverage, mortgage protection, permanent insurance, final-expense coverage, or business protection.
Start with the problem, not the product. Figure out which one you actually have before you get into coverage types.
We can't know exactly how long we'll live, how long we'll work, or whether our plans will unfold on the timeline we expect. What we can do is recognize that different risks call for different kinds of protection, and that the right protection should change when the life around it does.
If you're not sure whether your current coverage still matches your life, that's worth a conversation. Reach out to Chad Mitchell at Metropolis Financial Strategies to look at what you have against what's actually changed.